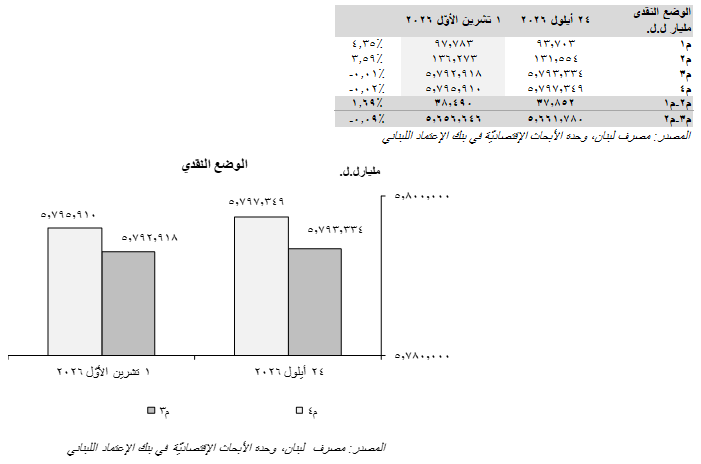

The overall money supply, “M4”, narrowed by LBP 1,438.97 billion during the week of October 1 to LBP 5,795.91 trillion, noting that the non-banking sector’s Treasury bills portfolio decreased by LBP 1,023.55 billion during the concerned week following due maturities of treasury bills held by public institutions.
In parallel, Lebanese-Pound denominated deposits and currency in circulation, “M1”, widened by LBP 4,080.61 billion week-on-week to LBP 97,783 billion on the back of the LBP 2,530.88 billion increase in demand deposits coupled with the LBP 1,549.73 billion rise in currency in circulation. Local currency term deposits, “M2”, also increased by LBP 4,718.72 billion on a weekly basis to settle at LBP 136,273 billion.
Consequently, private sector term and saving deposits denominated in LBP (“M2-M1”) widened by LBP 638.11 billion (1.69%) to LBP 38,490 billion during the week of October 1 while deposits denominated in foreign currencies (“M3-M2”) dropped by LBP 5,134.13 billion (0.09%) to LBP 5,656.65 trillion.
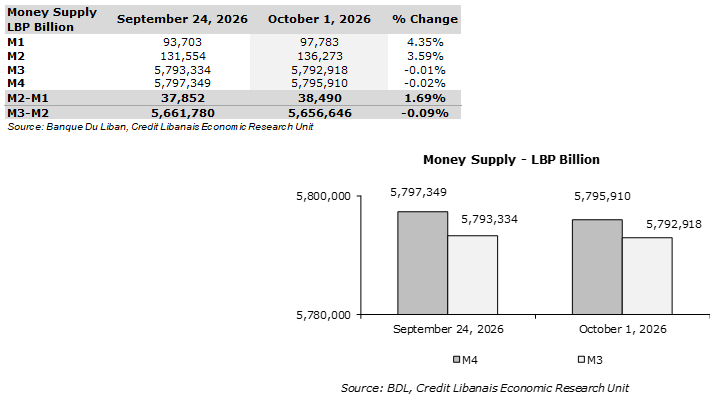
انخفضت الكتلة النقديّة بمفهومها الواسع، "م4"، ب1،438.97 مليار ل.ل. في الأسبوع المنتهي في 1 تشرين الأوّل إلى 5،795.91 ترليون ل.ل. علماً أنّ محفظة سندات الخزينة المكتتَب بها من قِبَل القطاع غير المصرفي قد تراجعت ب1،023.55 مليار ل.ل. في الأسبوع المذكور نتيجة استحقاق سندات خزينة للمؤسّسات العامّة.
في المقابل، ارتفعت الكتلة النقديّة "م1"، والتي تشمل السيولة الجاهزة بالليرة اللبنانيّة، ب4،080.61 مليار ل.ل. على أساسٍ أسبوعيٍّ إلى 97،783 مليار ل.ل.، وذلك بفعل زيادة حجم الودائع تحت الطلب ب2،530.88 مليار ل.ل. ترافقاً مع ارتفاع حجم النقد المتداول ب1،549.73 مليار ل.ل. وقد زادت الكتلة النقديّة بالليرة اللبنانيّة، "م2"، ب4،718.72 مليار ل.ل. لتصل إلى 136،273 مليار ل.ل.
في هذا الإطار، زاد حجم الادّخار بالعملة الوطنيّة (م2-م1) ب638.11 مليار ل.ل. (1.69%) إلى 38،490 مليار ل.ل. في الأسبوع المنتهي في 1 تشرين الأوّل فيما تراجع رصيد الودائع المعنونة بالعملات الأجنبيّة (م3-م2) ب5،134.13 مليار ل.ل. (0.09%) إلى 5،656.65 ترليون ل.ل.